The HALO Trade: Why Physical Assets Are Winning Over Software in 2026
Understanding the Shift from Digital to Physical
The investment landscape is undergoing a profound transformation. For the past decade, investors have favored “asset-light” companies—think software platforms and digital services that require minimal physical infrastructure. But in 2026, this preference is reversing dramatically. The market is now rotating toward “asset-heavy” industries: companies that own tangible infrastructure, physical networks, and hard assets that can’t be easily replicated.
This shift is called the HALO trade (Heavy Assets and Low Obsolescence), and it represents one of the most significant portfolio reallocations in recent memory.
Performance of US Asset Heavy (High Capital Expense to Sales ratio) to Asset Light FTW SPX Stock Indices – Past 6 Months, August 2025 to February 2026
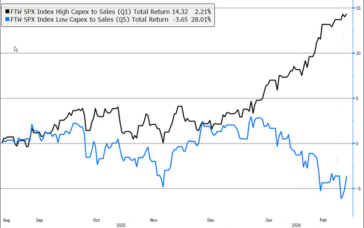
Source: Bloomberg. The above chart shows the outperformance in names that are asset heavy (high capital expense to sales ratio) versus companies that are asset light over the previous 6 months.
Why AI Changed Everything for Software Companies
The catalyst for this change is straightforward: artificial intelligence has fundamentally disrupted the software industry’s competitive advantage.
For decades, software companies enjoyed exceptional profit margins because building quality software required specialized talent, significant time investment, and deep technical expertise. These barriers to entry protected established players like Salesforce, Adobe, and ServiceNow from aggressive competition.
That protection is now gone.
Agentic AI—artificial intelligence systems that can independently write code, manage complex systems, and deploy solutions—has democratized software development. What once took a team of engineers months to build can now be generated by AI in days or weeks. The cost to launch a new software business has plummeted.
This creates a critical problem for established SaaS (Software-as-a-Service) companies: their historically high profit margins are now a target. AI-powered startups can undercut prices, replicate features faster, and compete on terms that were previously impossible. As competition intensifies, those attractive margins will inevitably compress.
The Market’s Response: Repricing SaaS Valuations
Investors are responding rationally to this threat. If software companies face margin compression and increased competition, their long-term profit potential—what analysts call “terminal value”—must be reassessed downward.
This is why we’re seeing valuation multiples compress for software and digital service companies. The market is essentially saying: “We’re less confident in your competitive moat.”
Meanwhile, companies with physical assets—power generation facilities, transportation networks, energy infrastructure, and manufacturing equipment—are gaining favor. Why? Because these assets have inherent protection:
- High replication costs: You can’t easily build a competing power grid or oil refinery
- Long technology cycles: Physical infrastructure remains relevant for decades
- Tangible value: Underground reserves, proprietary equipment, and global networks create genuine scarcity
The Irony: Tech Giants Become Capital-Intensive
Perhaps the most striking development is that the very companies that pioneered the asset-light model—Alphabet, Amazon, and Microsoft—have become the world’s largest capital spenders.
In 2026, these three hyperscalers are expected to invest approximately $500 billion in capital expenditures, representing roughly 32% of their combined sales. They’re building massive data centers, fiber-optic networks, and semiconductor facilities to power AI computing.
The message is clear: Even tech giants recognize that sustainable competitive advantage now requires physical infrastructure.
What This Means for Your Portfolio
The HALO trade reflects a rational reassessment of where value actually resides in the modern economy. Asset-heavy portfolios have significantly outperformed asset-light ones since early 2025, and this trend appears structurally sound.
For investors, this suggests:
- Diversification matters: Overweight positions in pure-play software may face headwinds
- Physical assets offer stability: Infrastructure, energy, and industrials provide tangible value protection
- The digital economy still needs physical foundations: AI and cloud computing require massive physical infrastructure—companies providing that infrastructure benefit from essential, hard-to-replicate assets
The rotation away from SaaS leadership toward physical asset ownership isn’t a temporary market whim. It reflects fundamental economic realities: in an era of abundant digital capacity and AI-driven competition, the assets that matter most are the ones that can’t be easily copied.
Q4 2025 Strategy & Market Reviews
Each quarter, our Investment Management teams publish their key observations and portfolio updates across Global Equity and Fixed Income markets. This is a summary of our views for the Fourth Quarter of 2025. You can download the full reports via the links shown below.
KEY OBSERVATIONS
The fourth quarter of 2025 marked a pivotal period for global markets as central banks worldwide delivered their most aggressive easing campaign since the financial crisis, with nine major central banks implementing 32 rate cuts totaling 850 basis points throughout the year. This unprecedented monetary stimulus, combined with ambitious fiscal programs across multiple regions, created a supportive backdrop for equity markets despite elevated valuations and periodic volatility.
Corporate earnings emerged as a key driver of market performance, with the S&P 500 delivering 13.6% year-over-year earnings growth in Q3—well above the 7.9% initially expected. More importantly, earnings strength broadened significantly beyond the technology sector, with 82% of S&P 500 companies exceeding earnings estimates, the highest rate since Q2 2021.
International markets demonstrated notable strength relative to U.S. equities, with Europe and Japan generating total returns of 20.7% and 25.5% respectively for the full year 2025, compared to 17.9% for the S&P 500. This outperformance was supported by significant fiscal stimulus initiatives, including Germany’s unprecedented €1 trillion infrastructure package, Japan’s ¥21.3 trillion spending program, and Canada’s ambitious five-year plan to mobilize roughly $1 trillion in public and private investment. These coordinated fiscal efforts, combined with accommodative monetary policy, are expected to provide sustained economic support through 2026.
Perhaps the key wild card remains the White House, as markets can never fully anticipate political developments. Events such as Liberation Day, which drove markets down nearly 20% from their recent high, were an unwelcome reminder of this uncertainty. That said, presidential approval ratings between 35% and 50% have historically been followed by average market gains of approximately 12.19% over the subsequent year. Seems counterintuitive, but perhaps some unpopular decisions might ultimately be good for the economy and markets.
In summary, the combination of resilient economic growth, positive earnings momentum, and the prospect of further interest rate cuts by the U.S. central bank continues to support our favourable outlook on equities going forward.
NORTH AMERICAN EQUITY UPDATE
Peter Jackson, HBSc, MBA, CFA
Chief Investment Officer
Portfolio Manager, North American Equities
Our overall equity exposure increased modestly from 98% to 99%, while cash declined from 2% to 1% since September 30, 2025. Within equities, U.S. exposure decreased from 57% to 53%, while Canadian equity exposure increased from 41% to 46%. Many client portfolios are invested through our North American plus International Equity strategy, which remains at 80% US/Canada and 20% International equities currently; as a result, the effective weights of U.S. and Canadian equities within total equity allocations are proportionally lower due to exposure to international markets.
In our North American strategy, we established the following positions:
Netflix (NFLX) was added based on conviction that the company can organically grow revenue at a mid-teens rate with earnings per share expanding at roughly twice that pace, driven by scaling of the advertising-supported tier, expansion into live events and gaming, and potential acquisition of Warner Bros.’ valuable IP portfolio.
PulteGroup (PHM) was added this high-quality U.S. homebuilder positioned to benefit from a structural housing shortage of approximately five million units and potential mortgage rate declines, trading at roughly 11x forward earnings with a 7.6% free cash flow yield.
Sprott Uranium Miners ETF (URNM) provides exposure to uranium producers positioned to benefit from an estimated 44-million-pound supply shortfall in 2026 and a cumulative 1.8-billion-pound deficit over the next 20 years as demand accelerates globally.
Shopify (SHOP) is a Canadian e-commerce platform offering comprehensive merchant solutions with high switching costs, recently partnering with OpenAI to enable direct sales through ChatGPT conversations, with revenue having grown 31% annually over the past five years.
A detailed review of each holding can be found in the full report per the link above.
GLOBAL EQUITY UPDATE
Phil D’Iorio, MBA, CFA
Portfolio Manager, Global Equities
Global equity markets demonstrated resilience in Q4 2025, with most developed markets generating positive returns despite periodic volatility. International markets significantly outperformed U.S. equities, with Europe’s Euro Stoxx 600 advancing 6.5% and Japan’s Tokyo Stock Exchange gaining 8.8% during the quarter, compared to 2.7% for the S&P 500. The year 2025 proved particularly strong for international investors, with Europe delivering a total return of 36.8% and Japan 25.5%, substantially ahead of the S&P 500’s 17.9% return.
The outlook for 2026 remains cautiously optimistic, supported by unprecedented monetary easing with 850 basis points of rate cuts from major central banks in 2025, significant fiscal stimulus programs including the U.S. One Big Beautiful Bill Act ($4.5 trillion in tax breaks over a decade), Germany’s €1 trillion infrastructure package, and Japan’s ¥21.3 trillion spending initiative. Corporate earnings momentum has been strong globally, with the percentage of companies beating earnings estimates in Q3 2025 exceeding historical medians across Europe, Japan, and Emerging Markets. The broadening of earnings growth beyond mega-cap technology stocks, combined with accommodative policy support and a capex supercycle led by artificial intelligence investments, creates a favorable environment for global equities despite elevated U.S. valuations and geopolitical uncertainties.
New positions added to the Global Strategy:
Ametek is an American industrial technology company manufacturing advanced electronic instruments and electromechanical devices for mission-critical applications in aerospace, energy, medical equipment, and industrial automation, operating in specialized niche markets with high barriers to entry.
Dollarama is Canada’s largest dollar store chain with over 1,600 domestic locations and growing Latin American presence through 60.1% ownership of Dollarcity, differentiated by broad income appeal, high private label mix, and exclusion of perishable items requiring refrigeration.
JPMorgan Chase is the largest U.S. bank with over $4 trillion in assets, operating as a universal bank with dominant presence across consumer banking, investment banking, and asset management, led by CEO Jamie Dimon’s disciplined risk management and fortress balance sheet approach.
UnitedHealth is a former position that is being re-added to the portfolio following management changes including former CEO Stephen Hemsley’s return to repair operations and reprice unprofitable business lines.
Netflix, PulteGroup, Sprott Uranium Miners ETF, and Shopify are described in the North American Equity section above.
New positions added to the International Strategy:
Hermès International is a renowned French luxury goods company positioned at the top echelon with iconic products like Birkin and Kelly bags, enjoying strong pricing power through exclusivity, high direct-to-consumer mix, vertical integration, and family control ensuring strategic consistency.
Orix is a major Japanese diversified financial services group transforming from leasing and corporate finance into an alternative asset manager focused on fee-related earnings, well-positioned to capitalize on succession opportunities in Japan’s mid-market under new CEO leadership.
Pan Pacific International is a Japanese retail holding company operating Don Quijote and other discount formats using a treasure hunt model with store manager autonomy, expanding its discount model and private label penetration across the Asia-Pacific region.
TE Connectivity is a global industrial technology leader providing connectivity and sensor solutions for automotive, networking, and industrial applications, benefiting from secular trends in datacenter capex, defense spending, renewable energy, and factory automation.
A detailed review of each company can be found in the full report per the link above.
FIXED INCOME UPDATE
Owen Morgan, MBA, CFA
Portfolio Manager, Fixed Income
The fixed income market delivered mixed results in Q4 2025 as the yield curve steepened, with short-term rates declining following the Bank of Canada’s October rate cut to 2.25% while long-term yields rose on stronger-than-expected employment and GDP data.
This dynamic created headwinds for government and provincial bonds, which posted small negative returns as bond prices fell in response to rising yields. However, corporate bonds emerged as the quarter’s standout performers, with both investment-grade and high-yield securities delivering positive returns as credit spreads tightened, reflecting growing investor confidence in corporate borrowers’ ability to service their debts.
Looking ahead to 2026, the fixed income strategy emphasizes high-quality investment-grade corporate bonds with select high-yield opportunities where conviction is strong.
With inflation stabilizing at the Bank of Canada’s 2% target and market expectations pricing minimal probability of significant rate cuts—approximately 60% chance of one small cut by year-end, earliest in mid-summer—the portfolio maintains flexibility on duration without extending into longer-term bonds unless spreads become significantly more attractive.
While corporate bond spreads currently sit below historical averages, the absence of recession warning signs and adequate Canadian economic performance support the credit-focused approach, positioning the portfolio to generate steady income while managing risk in an environment where companies remain on solid financial footing.
Given this environment, we’re maintaining a strategic approach. We are emphasizing high-quality investment-grade corporate bonds to capture attractive yields, with select opportunities in carefully chosen high-yield bonds where we have strong conviction. We are not extending into longer-term bonds yet, but if long-term rates become significantly more attractive relative to short-term rates, we’ll adjust accordingly.
While 2026 will bring both challenges and opportunities, we are cautiously optimistic, and believe the current environment supports our credit-focused strategy.
A detailed review of each company can be found in the full report per the link above.
Fourth Quarter 2025 Fixed Income Strategy Review
Your Fixed Income Portfolio: What Happened in Q4 2025 and What It Means for You
Your fixed income investments delivered mixed but overall positive results in the fourth quarter.
While government bonds faced some headwinds, corporate bonds performed well—a trend we expect to continue into 2026.
Here’s what drove these results and how we’re positioning your portfolio going forward.
Fourth Quarter 2025 Global Equity and International Review
Global stock markets generated strong gains during the fourth quarter of 2025 with most of the major developed market regions delivering positive returns. The key factors that drove performance included interest rate cuts from global central banks, strong corporate earnings, and economic resilience across major global economic regions. One of the key trends during the fourth quarter was the underperformance of U.S. stocks relative to international stocks. In the U.S., the S&P 500 generated a total return of +2.7% despite multiple selloffs in the technology sector that sent the overall market into negative territory in October and November. Performance was much stronger across many international markets with Europe and Japan generating total returns of +6.5% and +8.8%, respectively, as seen in the chart below.
Fourth Quarter 2025 North American Equity Strategy
During the fourth quarter, the S&P500 total return was +2.65% in U.S. dollars. Adjusting for currency, the S&P500 returned +1.17% in Canadian dollars, as the Canadian dollar appreciated 1.02 cents during the quarter to $0.7286. The TSX total return was +6.25% in the fourth quarter.
After two interest rate cuts in the U.S. in September and October, the Federal Reserve cut rates by another 25 basis points (0.25%) for the third time in December 2025. The December cut was generally viewed as a hawkish cut, meaning the Fed was viewed as cautious about additional cuts as the Federal Open Market Committee (FOMC) appeared divided, with six of the 19 members favouring no cut. Fortunately, four of the six who favoured no cut are not currently voting members. Still, two members dissented, which can sometimes be associated with turning points in policy decision-making.
This division may reflect the significant shift in the economic outlook for 2026 in the FOMC’s Summary of Economic Projections (SEP) (Exhibit 1). The outlook for real GDP was revised higher to 2.3% from 1.8% in the September projections. A positive takeaway from the SEP was the downshift in the inflation outlook. PCE inflation (the Feds preferred measure) is expected to decline to 2.4% in 2026 from 2.9% in 2025, an improvement from the September forecast of 2.6% for 2026. The SEP also shows inflation falling further to 2.1% in 2027, close to the Feds 2% target, as the one-time transitory tariff impacts roll off. The forecast for the unemployment rate in 2026 was unchanged at 4.4% from the September SEP. Overall, the stronger growth, lower inflation, and relatively low unemployment forecast are not a bad way to start 2026 all while interest rates could still come down somewhat as the December SEP continues to project another rate cut in each of 2026 and 2027.
Second Quarter 2025 Fixed Income Strategy Review
April was a tense month, beginning with the Liberation Day announcement by the US President on April 2. The proposed tariffs were broader, deeper higher than most analysts’ expectated.
The Treasury Bond market reacted strongly (a recap stated it “went into convulsions”). The 10-Year Treasury Bond yield rose 64 basis points in two days, a major move for a market where high single-digit moves in a day are more common. Rising bond yields mean falling bond prices. Treasurys lost more than 5% in value in one week.
It was the most volatility experienced in the fixed income markets since the pandemic shock in March 2020.
As a result, tariff proposals were quickly put on hold on April 9th by the US Administration. Over the ensuing weeks a seeming détente settled over the market as the rhetoric cooled somewhat (with the occasional notable hiccup) and investors grasped the impact of a world with tariffs in place.
Second Quarter 2025 Global Equity and International Review
Global stock markets began the second quarter of 2025 with a sharp sell-off. The losses were triggered by the tariff-related shock that resulted from Donald Trump’s Liberation Day announcement. This announcement was made on April 2 when most global stocks markets were closed. President Trump’s announcement included a series of tariffs that were materially higher than most analyst estimates. This led to a significant spike in market volatility the following day as the S&P 500 fell by nearly 5% while the Nasdaq plunged by close to 6%. International markets were also hit by the tariff announcements with the Euro Stoxx 600 index falling 2.6% and the Nikkei 225 falling nearly 3% in the trading session that followed Liberation Day. Stock market losses accelerated the following week with global indices plunging on Monday April 7th. The Euro Stoxx 600 index fell 4.5% while the Nikkei 225 fell nearly 8%. The heightened volatility was driven by several concerns including the potential for trade wars, rising geopolitical tensions, and tighter financial conditions triggered by rising bond yields. However, the global stock market rout was very short lived because on April 9th, President Trump announced 90-day pause on most tariffs. This pivot by President Trump set the stage for a huge rally in global equity markets in the months that followed. This allowed most of the major developed world stock markets to finish the second quarter in positive territory.
Second Quarter 2025 North American Equity Strategy
From its high on February 19, 2025, the S&P500 bottomed April 8th down -18.9% (Exhibit 1). Technically we avoided a bear market during the second quarter 2025, defined as greater than a -20% drop, as the S&P500 recovered from Trump’s April 2nd Liberation Day surprise with the announced 90 day pause on reciprocal tariffs announced on April 9th. With that reprieve, the S&P500 fully recovered to its previous high by the end of the second quarter. Meanwhile, the TSX hit new highs during this quarter. The S&P500 total return was +10.94% in U.S. dollars. Adjusting for currency, the S&P500 returned +5.15% in Canadian dollars, as the Canadian dollar increased US +3.99 cents over the same time frame to US $0.7349 . The TSX total return was +8.53% in the second quarter.
The Growing Appeal of European Equities
European equities have spent the past decade (2014-2024) in the shadow of U.S. and other developed world stock markets. In fact, European stocks lagged most of the large, developed world equity markets by a very wide margin as seen in the table below.
| Security | Currency | Price Change | Total Return |
| S&P 500 Index | USD | 183.94% | 239.95% |
| S&P ASX 200 | AUD | 52.03% | 160.69% |
| Tokyo Stock Exchange TOPIX | JPY | 97.86% | 148.83% |
| S&P/TSX Composite Index | CAD | 68.17% | 128.44% |
| STOXX Europe 600 Price Index EUR | EUR | 48.04% | 107.07% |
Source: Bloomberg (12/30/2014 – 12/30/2024)
As measured by the broad Stoxx Europe 600 index, European stocks generated less than half of the return of the S&P 500 (a leading U.S. index) from 2014-2024. European equities also lagged Japan, Australia, and Canada, by a significant amount as seen in the table above.
Some of the key factors that have caused Europe’s stock markets to underperform include sluggish economic growth, a lack of innovation, a weak banking sector, and Germany’s debt brake. All of these factors collectively acted as headwinds for Europe’s economy. However, many of these headwinds are now turning into tailwinds, which makes us more enthusiastic about the outlook for European equities in the years ahead.
Before we discuss the positive changes, it is worth revisiting some of the headwinds that led to Europe’s underperformance. The Great Financial Crisis (GFC) in 2008-09 is a good place to begin. While regulators in the United States moved quickly to stabilize their banking sector in the aftermath of the GFC, Europe’s path to recovery was very drawn out and filled with turbulence. In the years following the GFC, Europe went from crisis to crisis with several countries and banks flirting with the prospect of a default. Political upheaval including the Grexit and the Brexit, and other similar events also put stress on the system. To make matters worse, this upheaval was compounded by weak economic growth. This was happening at a time when the European Central Bank held interest rates in negative territory for nearly seven years. This put stress on the banking system by depriving them of their ability to generate sufficient net interest income. This in turn, had a negative impact on their willingness to lend. Taking all of this together, we can call it a negative feedback loop that helps to explain why Europe underperformed other parts of the developed world for the last decade.
But at the beginning of 2025, things started to change. Europe went from a laggard to a leader in terms stock market performance among the large, developed world economies. This can be seen in the table below.
| Security | Currency | Price Change | Total Return |
| STOXX Europe 600 Price Index EUR | EUR | 5.76% | 6.52% |
| S&P/TSX Composite Index | CAD | 1.21% | 2.04% |
| S&P ASX 200 | AUD | -4.76% | -3.35% |
| Tokyo Stock Exchange TOPIX | JPY | -4.53% | -3.37% |
| S&P 500 Index | USD | -5.00% | -4.68% |
Source: Bloomberg (12/30/2024 – 03/31/2025)
While there are many questions about the sustainability of Europe’s performance in the first quarter of 2025, we believe there are positive catalysts on the horizon. Looking forward, the region is set to benefit from lower interest rates, fiscal stimulus, and various initiatives related to investments and competitiveness. Furthermore, Europe’s banking system has returned to a healthy position. This is best exemplified by the fact that European banks have been one of the best performing sub-sectors in Europe over the last 2 years. In fact, from 2022-2024 the European Banks sector outperformed all of the large, developed market indices referenced in this piece. This can be seen in the Appendix.
In terms of monetary policy, the European Central Bank (ECB) cut interest rates by 25 basis points to 2.25% in April. This was the seventh interest rate cut in the current cycle and there are further rate cuts expected. Cutting interest rates should provide a tailwind to economic growth, which would potentially boost stock market returns. Europe’s interest rate cutting cycle stands in contrast to the United States where the interest rate cutting cycle has been on pause since January of this year. Inflation has been more persistent in the United States, so the U.S. Federal Reserve Bank has been reluctant to cut interest rates beyond the initial cuts that began last September.
When it comes to fiscal policy, a significant announcement was made in Germany a few months ago. On March 18, 2025, Germany’s Federal Parliament voted in favour of a landmark bill that plans to unlock hundreds of billions of euros for defence and infrastructure projects. The passing of this bill marks one of the largest fiscal policy shifts in postwar Germany given its decision to relax the debt brake. The debt brake was a constitutional fiscal rule put in place in the aftermath of the Great Financial Crisis (GFC). The debt brake limited government borrowing to 0.35% of GDP, which has acted as a headwind towards capital expenditures since the GFC in 2008-09. As a result of the debt brake, Germany has debt levels far below other countries around the world. Germany’s debt-to-GDP ratio is 62%, which compares with the United States at 124%. Given its low debt level, Germany has considerable room to manoeuvre with fiscal policy. From our perspective, Germany’s new-found commitment to fiscal stimulus should mark the beginning of a renewed cycle of capital and infrastructure investment. This is significant given that Germany is the largest country in the Eurozone. We believe that its spending in the years ahead should have positive flow through impacts to other countries throughout Europe.
In addition to monetary stimulus and Germany’s fiscal stimulus bill, several initiatives have been announced in recent years to boost Europe’s economy. The European Commission recently launched a new Competitiveness Compass, an initiative to improve economic growth in the Eurozone focusing on innovation, decarbonisation, and security. In addition, there is also the Next Generation EU program, which is considered one of the largest economic stimulus packages ever financed in Europe. The size of Next Generation EU is approximately €800 billion, which will be invested across many different areas including digital transformation, healthcare, and the green transition. In addition to the Competitive Compass and the Next Generation EU, there is also the European Chips Act. This Act was designed to increase the region’s position in the globally important semiconductor industry.
On top of all the catalysts outlined above, European stocks also trade at a significant discount relative to the United States based on historical levels as seen in the chart below.
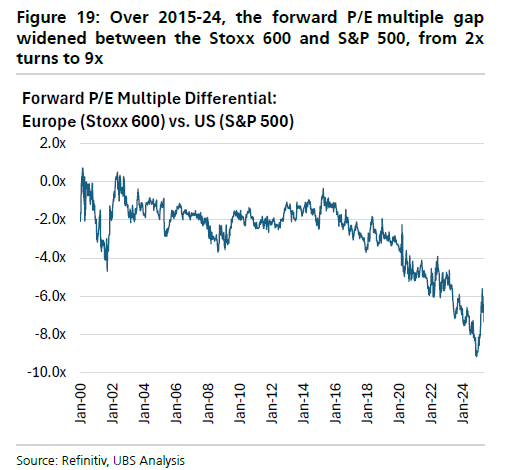
The valuation discrepancy illustrated in the chart above utilizes the price-to-earnings (P/E) ratio. From 2000 to 2016, Europe traded a 2 P/E multiple point discount to the United States. But starting in 2020, the European discount widened significantly and reached a high of 9 P/E multiple points in 2024. Given the rally in Q1 2025 for European stocks, the discount has recently narrowed to about 6 P/E multiple points. However, the discount remains well above the historical average.
In summary, we believe that the outlook for European equities is more promising than it has been in a long time. From our perspective, Europe sits at the centre of a global realignment that has been unfolding over the last few years. This realignment was recently reinforced when the U.S. announced it would withdraw some of its overseas spending on global security. This shift has prompted a significant increase in European government spending, particularly on defence. Looking forward, we believe there are significant catalysts that will provide tailwinds for European stocks in the years ahead. These tailwinds include monetary and fiscal policy, as well as various initiatives that will foster economic growth throughout Europe. We have been positioning our Global and International portfolios to take advantage of the opportunities that lie ahead for Europe.
Appendix
| Security | Currency | Price Change | Total Return |
| iShares STOXX Europe 600 Banks | EUR | 51.01% | 68.02% |
| STOXX Europe 600 Price Index EUR | EUR | 18.82% | 27.16% |
| S&P 500 INDEX | USD | 53.85% | 58.49% |
| Tokyo Stock Exchange TOPIX | JPY | 47.22% | 54.49% |
| S&P / TSX Composite Index | CAD | 27.01% | 35.34% |
| S&P/ ASX 200 | AUD | 17.00% | 29.66% |
Source: Bloomberg (12/30/2022 – 12/30/2024)
Beyond Bull and Bear: A Clear View of The Market
In 2010, as investors were still reeling from the Great Financial Crisis, we offered a simple piece of advice: Don’t be a bull or a bear. Just be right. It was a reminder that successful investing isn’t about ideology—it’s about weighing the evidence and making decisions grounded in reality, not emotion.
Today, that philosophy matters just as much. After two years of double-digit gains, US equities were down close to -20% earlier this year, and are still underwater on a year-to-date basis.
| Equity Market Index | Q1 2025 12/31/24-3/31/25 |
Year to Date April 30, 2025 |
One Year to April 30, 2025 |
| TSX | +1.5% | +1.4% | +17.9% |
| S&P500 (USD) | -4.3% | -4.9% | +12.1% |
| S&P500 (CAD) | -4.4% | -8.8% | +12.5% |
| Morningstar Developed Mkts(ex. North America) TME | +6.9% | +7.3% | +13.0% |
Source: Bloomberg
Now, many are wondering: Does the volatility of 2025 represent a temporary correction as we navigate the U.S. trade standoff before resuming more-or-less normal economic activity, or are we on the verge of a more extended downturn?
Before we go further, let’s stop to consider what a bear market could actually look like. Research from Goldman Sachs suggests that there are three types of bear markets going back to the 1800s, defined by their causes as well as their average declines, lengths, and times to recover.
- Structural bear markets are the most severe. They are triggered by structural imbalances and asset bubbles. They average declines of -60% over three years or more and can take up to a decade to fully recover. Good examples are the 2000 Tech wreck and, more recently, the 2008 Global Financial Crisis.
- Cyclical bear markets are the most typical. They are a function of the economic cycle, triggered usually by inflation, rising interest rates, and falling profits. They average declines of about -31%, last about two years, and take around four years to fully rebound. A version of this occurred in 2022, although with corporate debt in check and US consumers largely locked-in at low mortgage rates, we avoided a recession.
- Event-driven bear markets are triggered by one-off events. They do not lead to a domestic recession. They are associated with average declines of about -27%, last only about eight months, and recover within a year. Examples could include a war, an oil produce shock, and the Covid pandemic. Leading up to Covid, the economy was in good shape, with low inflation and stable growth—very similar to today.
We’ll return to these bear market scenarios in our final analysis. For now, let’s review some of the strongest arguments for the bull and bear cases going forward.
The Bear Case
Let’s start with what could go wrong.
Consumer sentiment has plunged. In March, the University of Michigan Consumer Sentiment Index fell to its lowest level since November 2022, and well below consensus expectations. This marks the third straight month of decline, with many consumers citing high uncertainty about government policy, personal finances, inflation, and market conditions. Sentiment today sits at or below levels historically associated with recessions.
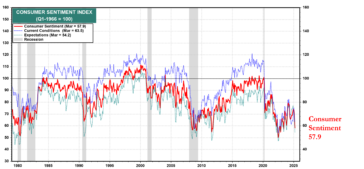
Source: Yardeni Research
Inflation expectations are also on the rise. In March, year-ahead consumer inflation expectations spiked to 4.9%, up sharply from 4.3% in February. Five-year inflation expectations rose to 3.9%, the largest one-month increase since 1993. Both measures sit well above the Federal Reserve’s target of 2%, suggesting that consumers are now more pessimistic than policymakers.
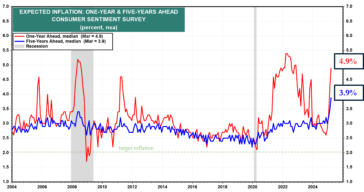
Source: Yardeni Research
If consumers pull back on spending in response to these fears, recession could prove to be a self-fulfilling prophecy.
Small businesses are sending similar signals. The National Federation of Independent Business (NFIB) Small Business Optimism Index marked its second consecutive monthly decline in February. Meanwhile, the NFIB Uncertainty Index rose to the second highest reading ever recorded.
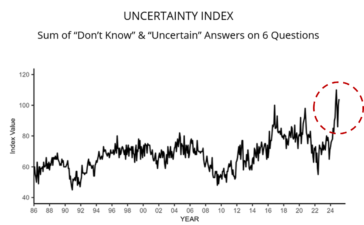
Source: National Federation of Independent Business (NFIB), February 2025 Small Business Economic Trends
According to the NFIB Chief Economist, “Uncertainty is high and rising on Main Street,” with inflation and labour quality ranking as the two biggest problems. Uncertainty has already begun to weigh on hiring and capital expenditure decisions, and unless it resolves, could further drag down growth.
Aggressive U.S. trade policies are clearly driving much of this uncertainty. As we have seen in past cycles, lack of clarity can paralyze corporate decision-making, disrupt supply chains, and slow capital expenditures. Should trade negotiations drag on or deteriorate further, the probability of a self-reinforcing downturn would increase materially.
In short, the bear case rests on deteriorating consumer and business confidence, rising inflation expectations, and political uncertainty. While much of this is based on “soft” data, such as surveys rather than hard economic statistics, it can still drive real-world behavior if uncertainty persists long enough.
The Bull Case
Now, on to what we think can go right from here.
After back-to-back US S&P500 equity market gains of over 20% in 2023 and 2024, what should we expect in year three of a bull market? History suggests returns tend to moderate but remain positive. As this chart shows, despite the wilder ride, net performance so far in 2025 is tracking closely to historical averages.
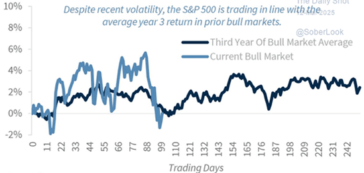
Source: Daily-Shot, Raymond James
Beyond the pattern of returns, hard economic data offers further support. Retail sales continue to show resilience. The Redbook Research weekly retail sales series shows that, as of mid-March, retail sales were up +5.5% year-over-year, reinforcing the view that consumers, despite political and policy-related uncertainty, are still spending.
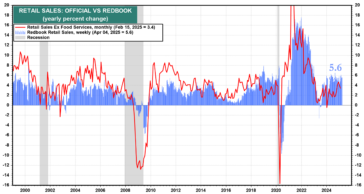
Source: Yardeni Research
This spending strength may be in part due to the strong labour market. Weekly jobless claims remain low at 241,000. This suggests strong job growth and limited layoffs. The unemployment rate, at 4.2%, is still well below the 50-year average of 5.8%, and only modestly above the 50-year low of 3.4% reached in 1969.
On the inflation front, market-based expectations remain relatively contained. The spread between nominal Treasury yields and Treasury Inflation-Protected Securities (TIPS) suggests an inflation outlook over the next five to ten years that is very close to the Fed’s long-term 2% target. This is far less alarming than the consumer survey data would suggest and gives the Fed room to maneuver if needed.
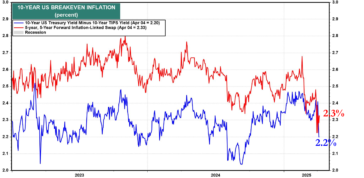
Source: Yardeni Research
Finally, the credit markets are not flashing recession signals. High-yield credit spreads remain well within their historical norms and have not widened meaningfully despite the recent equity market volatility. Canadian spreads have been even more stable, further supporting the notion that financial stress remains contained.
Taken together, muted but positive historical patterns, resilient consumer behavior, a strong labour market, well-anchored inflation expectations, and stable credit markets form the foundation for the bull case. While uncertainties remain, the underlying economic data remains on solid ground.
Which Bear Could it Be?
So far, we have a correction. At Cumberland, we’ve managed through numerous volatile periods over three decades. Today, we’re awaiting the resolution and potential impacts of the Trump 2.0 tariffs. The bullish view may well prevail.
If downside volatility continues, we believe it’s unlikely to morph into a structural or cyclical bear market. Economic fundamentals remain strong, and interest rates are more likely to fall than rise.
Therefore, we believe that any bear market will be of the event-driven variety, with the Liberation Day tariff shock as the instigating event. Given the historic size and scope of event-driven bear markets, most of the damage is likely already done. And, as a man-made event, it could all be reversed tomorrow.
Navigating From Here
Overall, US trade policy will dictate outcomes. But given the cross currents between sentiment and data, we are tilting portfolios toward a more cautious stance. We have modestly reduced our overall equity exposure, trimming positions in areas such as technology and industrials and adding to more defensive sectors, cash, and gold earlier.
However, it is important to note: we remain invested. History teaches that staying on the sidelines can be costly. Since 1950, the S&P 500 has been higher 74% of the time on a rolling one-year basis and 85% of the time over rolling three-year periods. Missing just a few of the market’s best days can severely diminish long-term returns.
Percentage of Time S&P 500 Rose Over Rolling Perions
1,3,5,10 and 15 Years from 1950-2024
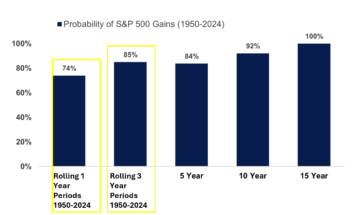
Source:LPL Research 03/11/25
Markets will continue to challenge our patience and our emotions. But in a world full of noise, our approach remains simple: eschew dogma, stay alert, lean on our long experience through many economic and market cycles, and follow the evidence through fundamental research and relevant data wherever it might lead.
