Why DIY Investors Eventually Seek a Financial Advisor
Self-directed investing has never been easier. Low-cost brokerages, robo-advisors, and an abundance of free research have given a generation of investors the tools to manage their own portfolios from day one. Yet the data tells a consistent story: many self-directed investors don’t stay self-directed forever. At some point, complexity, life events, or emotional strain push them toward professional investment management.
Understanding why and when this shift happens isn’t just academic. For advisors, it’s the roadmap to reaching investors at the exact moment they are ready to listen. For investors themselves, it’s a reality check, and a way to recognize the signs before any costly mistakes force the issue.
The Asset and Complexity Threshold
Managing a handful of index funds during the early accumulation years is relatively simple. However, as portfolios grow, typically somewhere between $250,000 and $1 million in investable assets, the cost of doing it yourself starts to rise.
At this stage, investors are more likely to be sitting on multiple accounts, unrealized gains, and decisions that carry real tax consequences. Once minor mistakes, such as poor asset allocation, missed tax-loss harvesting opportunities, and an inefficient contribution strategy can gradually become more expensive.
Life Events Are the Real Catalyst
Assets alone rarely trigger the switch to a financial advisor. It’s usually something happening in the investor’s life. Several patterns show up repeatedly in our conversations with new clients:
Capacity and risk. Investing isn’t just about picking stocks. Asset allocation and managing risk are crucial to maximizing risk-adjusted returns. Many clients transitioning from self-directed feel they no longer have the time or capacity to manage their investments.
Windfalls and wealth transfers. An inheritance, a business sale, a real estate transaction, or vesting equity all create sudden, high-stakes decisions with real tax consequences. These moments compress years of planning into a matter of weeks.
Family milestones. Marriage, divorce, estate planning for children, or becoming a caregiver for aging parents; all introduce financial complexity that a self-directed brokerage account was never designed to handle.
Volatility Wears People Down
Self-managed portfolios feel easy in a calm, rising market. That confidence erodes quickly when markets are volatile and in drawdowns. An advisor is often better equipped to assess a client’s risk tolerance than the client themselves. Some investors may say that they are comfortable with higher risk in their portfolios, but during volatile times, they tend to panic and want to get out of the market altogether. Recognizing their need for counsel, many investors began seeking professional advice in years like 2020 (COVID) or 2022 (inflation). Protection against downside risk is crucial to the risk management of a portfolio.
The Demand Is There — the Connection Isn’t
Perhaps the most interesting finding is the gap between interest and action. Many self-directed investors want access to a human specialist yet find themselves sitting in a queue on a platform with 50,000+ accounts, which can become aggravating. Human touch is a big motivator to make the move to professional advice.
The bottleneck is not demand; it is friction. Investors are often unsure when to seek advice or how to start the conversation without fully handing over control of their portfolio.
This gap is especially pronounced among younger investors. Gen Z and Millennial DIY investors are more likely than older generations to want a human advisor in the near term, even though this group is often assumed to be the most committed to going at it alone. Digital tools, it turns out, aren’t enough on their own to build full confidence around complex financial milestones.
The Hybrid Model Is the Endpoint, Not Full Handoff
Importantly, most investors don’t abandon self-directed investing entirely when they start working with an advisor. The more common pattern is a hybrid model: keeping a smaller, self-directed account for tactical trades or personal interest, while relying on a fee-only or comprehensive advisor for the core work — retirement planning, tax strategy, and estate considerations.
The Bigger Picture
| Stage of Wealth/Life | Key Characteristics |
| Early wealth building | Low complexity, cost-sensitive, DIY platforms |
| Asset & complexity growth | $250k–$1M+ portfolios, multi-account tax drag, growing interest in periodic validation |
| Decumulation & retirement | Sequence-of-returns risk, estate and tax planning, full or hybrid advisory relationship |
The people most likely to need help are often the ones searching for it. Conversations with professionals, particularly around these moments – a portfolio crossing $250k, a retirement date coming into view, a market downturn – are when the value of professional guidance becomes obvious. If you’d like to learn more about how we may be able to help, Schedule a Conversation with one of our Wealth Advisors.
Q2 2026 Strategy & Market Reviews
Each quarter, our Investment Management teams publish their key observations and portfolio updates across Global Equity and Fixed Income markets. This is a summary of our views for the Second Quarter of 2026. You can download the full reports via the links shown below.
Key Observations
During the second quarter, the S&P 500 posted a total return of +15.20% in U.S. dollar terms. After adjusting for currency effects, the return improved to +17.46% in Canadian dollar terms. The S&P/TSX Composite Index delivered a positive total return of +6.96% for the quarter.
Because today’s marketplace concerns are largely U.S.-centric, we are keeping a close eye on the macro factors shaping conditions, the AI-driven performance across technology and other sectors, and the implications for the outlook ahead.
In June, the U.S. Federal Open Market Committee kept the federal funds rate unchanged at 3.50%–3.75%. In response to a notable upward shift in inflation expectations for 2026, nearly half of policymakers—nine of the nineteen committee members—indicated support for at least one interest rate hike later this year.
Offsetting the potential negative effects of tighter interest rate policy expectations is the continued strength in corporate earnings momentum. S&P 500 operating Earnings per Share (EPS) rose +18.9% year-over-year in Q1 2026, more than double the long-run average of +8.7%. Market consensus is for this momentum to accelerate further into 2027 and 2028.
Global equity markets were strong during the second quarter of 2026, driven by better-than-expected economic activity, evidence of progress in negotiations between the U.S. and Iran, and another quarter of robust corporate earnings. Returns were positive across all major developed market regions, with many indices generating double digit returns.
We remain constructive on equity markets. Earnings growth remains robust, the economic outlook is generally positive, and valuation multiples have eased somewhat. Credit conditions in the U.S. remain neutral, and Fed projections suggest inflation could moderate into 2027. We will continue to monitor developments closely and refine positioning as conditions evolve in the weeks and months ahead.
North American Equity Update
Peter Jackson, HBSc, MBA, CFA
Chief Investment Officer
Portfolio Manager, North American Equities
Our overall equity exposure increased from 95% to 97%, while cash decreased from 5% to 3%. Within equities, U.S. exposure increased from 52% to 54%, while Canadian exposure remained unchanged at 43% over the same period. It is important to note that many client portfolios are invested through our North American plus International Equity strategy, which is currently allocated 80% to U.S. and Canadian equities and 20% to international equities. As a result, the effective weights of U.S. and Canadian equities within total equity allocations are modestly diluted due to this international exposure.
The Magnificent 7 (Apple, Microsoft, Amazon, Alphabet, Meta, Nvidia, and Tesla) have lagged the broader market this year. They were down -2.5% year-to-date , while the remaining S&P 493 stocks were up +15.6%. At the same time, volatility has increased, prompting us to closely monitor our AI exposure, including both technology holdings and “picks-and-shovels” beneficiaries such as Eaton Corporation. We have already trimmed some of these positions following their strong performance.
Our concerns centre on three areas: capital spending, capital issuance, and return on invested capital. The Big Four hyperscalers (Amazon, Alphabet, Meta, Microsoft) continue to increase AI-related capital expenditures. While their balance sheets remain exceptionally strong, the scale of these investments raises questions about future returns. At the same time, AI competition is intensifying, token consumption appears to be moderating, and lower-cost Chinese models are gaining traction.
With semiconductor valuations approaching dot-com-era levels and market leadership broadening beyond the Magnificent 7, we have continued reducing AI-related exposure and rotating into cyclical industrials and healthcare, adding to existing positions such as Union Pacific Corporation and Linde Plc., and initiating a new position in healthcare provider McKesson Corporation.
In our North American strategy, we established the following positions:
McKesson Corporation distributes drugs to pharmacies, hospitals, and clinics. The company delivers one out of every three prescriptions in the US. We see McKesson benefiting from a series of upcoming drug patent expiries. Over the next few years, some of the most successful specialty cancer drugs in the world are hitting a patent cliff, and McKesson is uniquely positioned to help doctors swap out expensive brand-name biologics for cheaper, higher-margin biosimilar alternatives.
Analog Devices is a global semiconductor leader specializing in high-performance analog, mixed-signal and digital signal processing technology. Gross margins, book-to-bill, and earnings momentum have all improved and we expect the trend to continue as the company’s products align with several long-term secular mega-trends including factory automation, robotics, electrification, advanced driver-assistance systems, and the expanding infrastructure demands of artificial intelligence.
A detailed review of each holding can be found in the full report per the link above.
Global Equity Update
Phil D’Iorio, MBA, CFA
Portfolio Manager, Global Equities
Global equity markets were strong during the second quarter of 2026, driven by better-than-expected economic activity, and as cited evidence of progress in negotiations between the U.S., and another quarter of robust corporate earnings. Returns were positive across all major developed market regions, with many indices generating double-digit returns.
The Middle East conflict led to renewed volatility in oil markets and reinforced the potential for higher input costs across the global economy. Despite these concerns, economic growth remained sufficiently firm to offset fears of an imminent slowdown. The number of cargo ships and oil tankers passing through the Strait of Hormuz increased significantly during the last few weeks of the second quarter.
Artificial intelligence remains one of the world’s most important drivers of capital investment. Demand for AI infrastructure continues to be strong, but AI is only one part of a broader global capital spending cycle also being driven by supply chain resilience, energy security, strategic independence, and defence spending.
Across Europe, activity proved more durable than anticipated, supported by improving real incomes, stabilizing manufacturing activity, and continued fiscal support. Japan’s economy remained on a firmer footing than many investors anticipated entering the year. Rising wages, improving business sentiment, and continued capital expenditure supported domestic demand.
One area of the global economy that has shown significant improvement is the manufacturing sector. The Manufacturing PMI index in the U.S., Europe, and Asia has inflected higher in 2026. All three regions currently have PMI readings comfortably above 50, which is the threshold between economic expansion and contraction. This has provided a tailwind to the global economy and is encouraging to see.
We enter the second half of the year with cautious optimism. The underlying drivers of growth include technological innovation, healthy labour markets, and continued corporate investment. In addition, corporate earnings expectations have generally moved higher, with positive earnings revisions becoming increasingly broad-based across sectors and regions. This trend has provided an important foundation for global equity markets despite elevated valuations in certain areas. Putting it all together, we have a constructive view on global equity markets.
New positions added to the Global Strategy:
As described above, Analog Devices is a global semiconductor leader specializing in high-performance analog, mixed-signal, and digital signal processing technology. Margins and earnings momentum align with long-term secular mega-trends including automation, robotics, electrification, advanced driver-assistance systems, and artificial intelligence.
Canadian Natural Resources Limited (CNQ) is the largest crude oil producer and the second largest natural gas producer in Canada, with smaller operations in the U.K. portion of the North Sea, and Offshore Africa. CNQ has increased its dividend 25 consecutive years with a 21% compound annual growth rate.
Galderma offers a science-based portfolio of brands and services for the global skin care industry. With above average market growth, opportunities to expand its operating margins, and new product launches, Galderma is well positioned for growth in the years ahead.
Keyence Corporation is a premier Japan-based global leader in the development and manufacturing of factory automation and inspection equipment. The company’s unique business model is difficult for competitors to replicate and has allowed the company to generate exceptional profitability and consistently high returns on capital.
McKesson also described above, provides essential delivery and logistics for the North American pharmaceutical supply chain. The company delivers one out of every three prescriptions in the US and is well positioned to benefit from a series of drug patent expiries in the years ahead.
MDA Space (MDA) is a 45-year-old Canadian world leader in space equipment manufacturing. MDA has established an excellent financial track record and is now facing large demands in the military and surveillance areas. The SpaceX IPO will only bring increased attention to the space economy and the MDA stock.
New position added to the International Strategy:
Amer Sports is a sporting goods manufacturer that owns the Arc’teryx, Salomon, and Wilson brands. The company expects to expand gross margins by over 200 basis points to 60% in the mid-term. With a solid balance sheet, a reasonable valuation, and strong earnings growth, we believe that Amer Sports shares look attractive.
A detailed review of each company can be found in the full report per the link above.
Fixed Income Update
Owen Morgan, MBA, CFA
Portfolio Manager, Fixed Income
Domestically, we remain in a sluggish economic environment. Inflation remains generally in line with the Bank of Canada’s target, despite the ramp-up in energy prices earlier in the year. Interest rates fluctuated to a small degree in the end, despite discussion about potentially wider swings.
With interest rates decreasing to a small degree, and with corporate spreads narrowing further, it was a positive quarter in general for fixed income securities.
Corporate bond spreads are now close to their all-time low. Investors are not bracing for financial strife. At the same time, there is less margin should an unforeseen shock occur. While spreads are tighter, the yields on corporate bonds are at or near their longer-term average of the past 10 years, and continue to be an attractive investment in our view.
In our previous note, we predicted that core inflation (excluding energy) would likely remain calm as domestic job growth remains weak and financial conditions are tightening. Indeed, the higher oil prices rise, the greater the negative feedback into the employment picture. Further, the looming CUSMA trade negotiations have continued to add uncertainty and quell economic activity.
Taken together, these factors serve as persuasive arguments for policymakers to stay on hold regarding interest rates. We think most of these points remain valid today.
Given our view remains more or less unchanged, our investment strategy remains aligned with prior quarters. We continue to emphasize high-quality, investment-grade corporate bonds for attractive yields, while adding select high-yield bonds where conviction is high. We are keeping duration on the shorter side, and will extend into longer-term bonds if longer term yields become structurally more compelling on a relative basis.
A detailed review of each company can be found in the full report per the link above.
Second Quarter 2026 Global Equity and International Review
Summary:
Global equity markets delivered impressive Q2 2026 returns, with the MSCI World Index gaining 13.9% despite geopolitical tensions and energy volatility. The S&P 500 led developed markets with a 15.2% total return, while European and Japanese indices posted double-digit gains.
Four key themes drove performance:
- economic resilience across major economies,
- AI infrastructure investment,
- strong corporate earnings,
- and de-escalating U.S.-Iran tensions.
Economic activity remained robust despite elevated interest rates, with consumer spending, labor markets, and business investment staying firm. Manufacturing PMI indices across the U.S., Europe, and Asia surged above the 50 expansion threshold, signaling broad-based economic momentum.
Artificial intelligence emerged as a critical growth driver, with capital investment broadening beyond tech leaders to encompass the entire AI value chain. Geopolitical considerations—including supply chain resilience and defense spending—further powered a global capex super cycle. Corporate earnings revisions have been consistently positive, with most major regions expected to achieve double-digit earnings growth in 2026.
Credit markets show minimal stress, with high-yield spreads remaining tight. However, the outlook carries notable risks: elevated stock valuations, persistent inflation concerns, ongoing geopolitical tensions, and potential volatility ahead of U.S. Midterm Elections. Despite these headwinds, the portfolio managers maintain cautious optimism, citing firm growth drivers including technological innovation, healthy labor markets, and broad-based earnings momentum. The constructive outlook reflects confidence in sustained global expansion through 2026.
Read the full article by clicking below.
Second Quarter 2026 North American Equity Strategy
Summary:
The second quarter delivered strong returns for U.S. equities, with the S&P 500 posting a +15.20% total return in USD terms, bolstered by exceptional corporate earnings momentum. Operating earnings per share surged +18.9% year-over-year in Q1 2026—more than double the long-run average—with consensus projections for continued acceleration through 2026 and 2027.
However, the investment landscape is shifting. New Federal Reserve Chair Kevin Warsh signaled a hawkish stance on inflation, with the FOMC’s June projections revealing upward revisions to PCE inflation for 2026 and nine of nineteen policymakers supporting at least one rate hike later this year. Markets have repriced accordingly, shifting from expectations of multiple rate cuts to pricing in potential hikes.
Despite tighter monetary policy headwinds, the economic backdrop remains resilient. Real GDP growth is tracking above Fed projections at 2.5%, while the labor market continues to expand at a pace consistent with 2023-2024 levels. Credit conditions remain neutral, signaling no imminent recession concerns.
The article highlights growing concerns around the “Magnificent 7” technology stocks, which have lagged the broader market year-to-date. The focus centers on three critical issues: massive capital spending requirements ($765B in 2026, potentially $1.6T by 2031), capital issuance pressures, and return on invested capital (ROIC) sustainability. Token pricing has doubled, yet consumption may be moderating, while competition from cheaper Chinese AI models intensifies.
In response, the portfolio has rotated from AI-exposed positions into cyclical industrials and healthcare, adding positions in Union Pacific and Linde, while initiating healthcare exposure through McKesson. Valuation multiples have compressed from 22.1x to 20.0x forward P/E, yet earnings growth has outpaced price appreciation, making markets cheaper despite significant gains. The outlook remains constructive, supported by broad earnings strength, market breadth improvement, and expectations for inflation to peak in Q3 2026.
Read the full article by clicking below.
Inflation and the AI Productivity Paradox
Kevin Warsh is the new Federal Reserve Chair. Appointed by President Trump, his vision for monetary policy offers a distinct contrast to the approach of his predecessor, Jerome Powell. Under Powell’s leadership, the Fed cautiously kept interest rates elevated to navigate a number of factors that are keeping inflation stubbornly above the 2% target: a resilient labor market, strong consumer spending, high fiscal deficits, tariffs, and now, renewed geopolitical uncertainty and the associated energy price shocks. However, Warsh has argued for a change of course. He believes high borrowing costs are no longer appropriate, especially as new technology promises to increase labor productivity.
How Productivity Prevents Inflation
Warsh’s main argument for cutting rates relies on the economic relationship between productivity and inflation. Higher productivity allows an economy to generate more output from the same amount of labor and capital. This creates wealth without triggering inflation because it fundamentally expands the economy’s aggregate supply to match rising incomes.
When output per hour increases, companies generate more revenue per worker. This allows them to increase wages and expand profit margins simultaneously. Because the economy is physically producing more goods and services, this additional income represents genuine purchasing power—an increase in real wealth and standard of living. Inflation only occurs when aggregate demand outpaces aggregate supply (too much money chasing too few goods). Productivity prevents this by ensuring the supply of goods grows alongside wages.
Warsh argues that the AI boom will expand the supply of goods and services fast enough to naturally keep prices down, giving the central bank reason to lower interest rates. However, capturing these deflationary benefits requires weathering the large, upfront inflationary costs of deploying new technology.
The 1990s Precedent
There is historical precedent for Warsh’s optimism. In the early 90s, despite the initial deployment of PCs and the internet, productivity growth remained mediocre, averaging approximately 1.5% per year—essentially the same pace the U.S. had seen throughout the 1970s and 1980s. But in the second half of the decade, as personal computers, the internet, and new telecom technologies became more deeply embedded into the workplace, productivity nearly doubled, averaging 2.5% to 3% per year. By the year 2000, productivity growth hit 4.3%.
Rather than raising rates to cool down a fast-growing economy, then-Fed Chair Alan Greenspan kept interest rates relatively low—mostly in a tight band between 4.75% and 5.5%. The strategy seemed to work initially as productivity gains came from the deployment of new technology.
The Warning: The Dot-Com Bubble and Rate Reversals
However, the full 1990s story comes with a warning. While Greenspan’s lower rates seemed to work at first, the stock market eventually overheated, leading to the dot-com bubble. To stop demand from spiraling out of control, Greenspan had to reverse course and raise rates aggressively in the year 2000, pushing them up to 6.5%. The bubble burst soon after. Today, the concern is if Warsh cuts rates too soon, he could accidentally fuel a similar bubble, forcing the Fed to hike rates later.
The Immediate Challenge: The Productivity J-Curve
We are still in the early days of the AI rollout. Tech companies are spending hundreds of billions of dollars to build data centers and buy enough electricity to run them. This huge spending spree risks driving prices up before we get the full benefits from increased productivity. Economists call this the “productivity J-curve.”
In the short term, adopting new technology costs a lot of money and drives up demand, which causes inflation. The promised efficiency gains—the part that brings prices down—only come years later. If Warsh cuts rates now expecting instant productivity, it could just be pouring gasoline on today’s inflation fires.
What This Means for Your Portfolio
For investors, success lies in balancing AI-driven growth with exposure to companies featuring strong free cash flow, pricing power, and the resilience to withstand potential delays in productivity gains. Beyond the tech sector, leading companies in industries like healthcare, industrials, and financials offer valuable inflation protection and portfolio diversification.
Q1 2026 Strategy & Market Reviews
Each quarter, our Investment Management teams publish their key observations and portfolio updates across Global Equity and Fixed Income markets. This is a summary of our views for the First Quarter of 2026. You can download the full reports via the links shown below.
Key Observations
During the first quarter, the S&P 500 posted a total return of -4.33% in U.S. dollar terms, which improved to -2.84% in Canadian dollar terms, while the S&P/TSX Composite Index delivered a positive total return of +3.94%, driven mainly by energy stocks. Current data indicate that economic growth is moderating but remains positive, the consumer continues to spend at a healthy pace, and credit markets are not signaling systemic stress.
The tone in the market changed significantly on February 28th when the United States and Israel launched airstrikes across Iran. While the conflict created heightened uncertainty, our base case is that the impact on the markets from the war will be short lived, supported by historical evidence showing the S&P 500’s typical trajectory around geopolitical events dating back to World War II. Even if the conflict ends quickly, a persistent war premium in the oil futures strip would likely benefit energy producers.
At its March meeting, the Federal Open Market Committee maintained the target range for the federal funds rate at 3.50%–3.75% and appears in no rush to lower interest rates. Meanwhile, the earnings backdrop remains strong and supportive of equities, with five consecutive quarters of double-digit earnings growth for the S&P 500 and strong forward earnings expectations for 2026 and 2027.
In Europe, Eurozone business activity accelerated faster than forecast in February as manufacturing swung back to growth for the first time since October. In Japan, the Bank of Japan’s quarterly Tankan survey reached its highest level since Q4 2021, while returns were also positive reflecting the enthusiasm of ongoing changes to corporate governance and a pro-growth mandate. In addition to positive economic indicators, corporate earnings were revised higher across most geographic regions in the early part of 2026, with Europe being the notable exception.
In summary, the combination of resilient economic growth, continued earnings momentum, and the prospect of a relatively swift resolution to the conflict has kept us constructive on equities going forward, despite elevated geopolitical uncertainty.
North American Equity Update
Peter Jackson, HBSc, MBA, CFA
Chief Investment Officer
Portfolio Manager, North American Equities
Our overall equity exposure decreased modestly from 99% to 95%, while cash increased from 1% to 5% during the quarter. Within equities, U.S. exposure edged down slightly from 53% to 52%, while Canadian exposure saw a more notable reduction from 46% to 43%. Many client portfolios are invested through our North American plus International Equity strategy, which remains at 80% US/Canada and 20% International equities currently; as a result, the effective weights of U.S. and Canadian equities within total equity allocations are proportionally lower due to exposure to international markets.
In our North American strategy, we established the following positions:
TJX Companies is a liquidation retailer with 5,200 stores today and plans to grow to 7,000 stores as it enters new markets in Europe and Latin America. We expect TJX to be able to consistently grow earnings at 10%+ for years to come through a combination of same-store-sales growth, store unit growth, and margin expansion.
Union Pacific Railroad is the second largest Class 1 railroad with industry-leading profitability. It is pursuing a merger with Norfolk Southern to establish the first US transcontinental railroad by the first half of 2027 which, if approved, will enhance its competitive advantages.
Canadian Natural Resources Limited is the largest crude oil producer and the second largest natural gas producer in Canada. Its vast reserves allow the company to generate substantial and sustainable free cash flow. CNQ has increased its dividend 25 consecutive years with a 21% compound annual growth rate.
Rockpoint Gas Storage has natural gas storage facilities in western North America (California and Alberta). Free cashflow conversion of EBITDA is high as they have little capital spending beyond modest maintenance. They have a small trading operation, which provides extraordinary additional profits in times of energy volatility like right now.
MDA Space is a 45-year-old Canadian world leader in space equipment manufacturing (they make the Canadarm robotic arm on the International Space Station). Industry demand has taken off in recent years with launch costs falling dramatically. The SpaceX IPO will only bring increased attention to the space economy and the more modestly priced MDA stock.
Gildan Activewear has historically dominated the activewear business. They recently acquired competitor Hanesbrands, which dominates an adjacent market of branded underwear. We see the integration of the two companies as a match made in heaven, allowing Gildan a low-cost entry into the branded retailer channel.
A detailed review of each holding can be found in the full report per the link above.
Global Equity Update
Phil D’Iorio, MBA, CFA
Portfolio Manager, Global Equities
Global equity markets got off to a good start in 2026. However, several global indices finished the first quarter with negative returns. Canada and Japan were able to buck this trend for different reasons. In Canada, returns were positive due to its large energy sector weighting. In Japan, positive returns reflected enthusiasm around its pro-growth mandate.
There were a lot of good things happening around the world just prior to the outbreak of the conflict involving Iran. Economic indicators had improved, corporate earnings revisions had turned positive in many parts of the world, and stock market performance had broadened out to more sectors. Corporate earnings were revised higher across most geographic regions, with Europe being the notable exception
Eurozone business activity accelerated faster than forecast in February as manufacturing swung back to growth for the first time since October. The Bank of Japan’s quarterly Tankan survey, a measure of manufacturer optimism, reached its highest level since Q4 2021. The global Purchasing Managers Index also turned up in the early part of 2026.
Our base case is that the war with Iran will be short-lived. President Trump has shown a tendency to respond to market stress, and U.S. midterm elections in the fall are an added incentive for him to de-escalate the conflict and come to a resolution. We are monitoring the situation carefully and will make adjustments to our portfolios as needed.
New positions added to the Global Strategy:
Investor AB is a leading Nordic industrial holding company with stakes in global firms such as Atlas Copco, ABB, and AstraZeneca. Its business model centres on active ownership and long-term operational excellence. We are attracted to its high-quality assets, disciplined approach, and strong long-term track record.
Hoya Corporation is a global med-tech and high-tech company with leading positions in eyeglass lenses, medical endoscopes, and semiconductor mask blanks. We are attracted to its dominant niche market positions and its consistent ability to generate high returns through disciplined capital allocation.
ASML Holding is the world’s sole provider of extreme ultraviolet lithography machines, making it a critical partner to the global semiconductor industry. We view the company as an indispensable supplier to leading chipmakers and a key beneficiary of continued investment in artificial intelligence.
Ferguson is the leading North American distributor of plumbing, heating, and pipe, valves, and fittings products. We are attracted to its scale advantages in a highly fragmented industry, which have consistently allowed it to capture market share from smaller local distributors.
Union Pacific Corporation operates one of the largest rail networks in North America, connecting 23 states across the western two-thirds of the United States. We are attracted to its high barriers to entry and the strength of its irreplaceable physical infrastructure.
Itochu Corporation is a premier Japanese trading company with a strong non-resource bias and meaningful exposure to stable consumer and retail segments. We are attracted to its resilient cash flow generation, diversified global footprint, and shareholder-friendly policy, including progressive dividends and frequent share buybacks.
Erste Group Bank is a leading financial services provider in the eastern part of the European Union, serving more than 16 million customers. We are attracted to its exposure to faster-growing Central and Eastern European economies, robust capital position, and conservative risk profile.
New positions added to the International Strategy:
BAWAG Group AG has transformed into one of the most efficient retail-focused banks in Europe with one of the lowest cost/income ratios in European banking. They complement organic growth with acquisitions and they continue to generate excess capital for share repurchases and future acquisitions.
DBS Group is the largest Southeast Asian Bank by assets with a 50% share in its native Singapore market and an increasing presence across Asia, particularly India and Indonesia. The company has strong exposure to trade flows across Asia along with a growing wealth management business.
Rakuten Bank is the fastest growing digital bank in Japan and well positioned to capitalize on the growing trend to cashless in Japan. The company will benefit from rising yields in Japan as the Bank of Japan is expected to increase interest rates twice this year.
Konami Group is a diversified entertainment giant. The company is the leading game developer and publisher in Japan. We expect it to deliver mid-teens earnings growth over the mid-term.
InterContinental Hotels Group operates an asset-light business model, focusing on franchising and managing hotels across a brand portfolio that includes Holiday Inn, Regent, and Crowne Plaza. With 342,000 rooms and a franchise model that drives high returns, we are positive on the long-term growth of the company.
Roche Holding is uniquely structured with two highly synergistic divisions: Pharmaceuticals and Diagnostics, We expect continued strong sales growth within pharma, and the diagnostics division should accelerate growth to mid-high single digits.
Nomura Research Institute Ltd is Japan’s first private think tank and a premier provider of IT solutions and consulting with a strong presence in Japan’s financial
sector. We expect mid-to-high single-digit revenue growth over the mid-term leading to strong and reliable earnings growth.
Tokyo Electron is a global leader in Semiconductor Production Equipment (SPE). With long-term low double-digit earnings growth driven by a strong backdrop for semiconductors, we remain positive on the outlook for Tokyo Electron.
Addtech sells components and systems across automation, electrification, energy, and industrial markets in Europe. The company has delivered strong low double-digit growth through organic expansion and bolt-on acquisitions. We believe its decentralized model and niche-market focus support attractive long-term prospects.
ALS is a global leader in testing, inspection, and certification services. The company is positioned to benefit from higher mining exploration as gold and metals prices rise. We believe its exposure to commodities and strong M&A pipeline support appealing growth in the current environment.
Daifuku is a leader in materials handling and automated logistics. The company is benefiting from manufacturing reshoring, labour-driven logistics automation, and AI data centre demand. We believe its leadership in semiconductor conveyance and growing services revenue support strong long-term growth.
Rheinmetall is a leading European defense company. Rising defense spending and German stimulus provide a strong tailwind for growth. We believe expanding capacity and the divestment of its auto business will allow the company to focus on its most attractive opportunities.
Boliden is a metals and mining company with operations in politically stable regions. Its smelting business provides stability, while rising demand for metals should support earnings growth. We believe steady operations and expansion of existing mines provide attractive upside.
Italgas is a leading gas distributor in Italy and Greece. The company is rolling out smart meters across its customer base and has expanded into water services and energy efficiency. We believe its core distribution business and new growth areas support attractive long-term prospects.
A detailed review of each company can be found in the full report per the link above.
Fixed Income Update
Owen Morgan, MBA, CFA
Portfolio Manager, Fixed Income
The fixed income market delivered modest but positive results in the first quarter. Government bonds outperformed, while corporate bonds lagged but still generated positive performance. During the quarter, interest rates initially drifted lower, as domestic economic growth could be described as tepid. This changed in late February with the uncertainty created by the military actions in and around Iran and the effect of attacks on Middle East energy infrastructure. Yields of Canadian benchmark bonds rose sharply, particularly at the short end, before stabilizing.
Higher interest rates and wider corporate bond spreads generally served as headwinds to fixed income returns. However, both investment-grade and high-yield corporate bonds delivered positive returns, as the increase in yields and spreads was modest enough that coupon payments more than offset them. While corporate bond spreads widened during the quarter, they remain tight relative to historical norms and do not suggest broad credit concerns.
Looking ahead, our view is that the Bank of Canada is likely to remain on hold. While the bond market is pricing in rate hikes over the next 12 months, we believe calm core inflation, weak domestic job growth, tighter financial conditions, and uncertainty around trade and energy prices support a more patient stance. Governor Macklem’s recent remarks also suggest that it remains premature to draw firm conclusions about the long-term impact of the oil shock.
Given this backdrop, we continue to emphasize high-quality investment-grade corporate bonds, with select opportunities in carefully chosen high-yield bonds where conviction is strong. We are not extending into longer-term bonds yet, but would become more constructive if long-term rates become significantly more attractive. Overall, we remain cautiously optimistic and believe the current environment continues to support our credit-focused strategy.
A detailed review of each company can be found in the full report per the link above.
First Quarter 2026 Global Equity and International Review
Summary:
Global equity markets experienced a volatile Q1 2026, marked by strong early momentum that reversed sharply following U.S.-Israel airstrikes on Iran on February 28th. The MSCI World Index declined 3.5% including dividends, while the S&P 500 fell 4.4%. However, Canada and Japan bucked the trend, posting positive returns of 4.0% and 3.6% respectively, driven by energy sector strength and pro-growth corporate governance reforms.
The primary catalyst for market weakness was disruption in the Strait of Hormuz, a critical energy chokepoint handling 21 million barrels of oil daily—20% of global petroleum consumption. Daily tanker traffic plummeted from 130-140 vessels to just 5-10, sending crude prices above $100/barrel. However, a 2-week ceasefire announced April 7th, with Iran agreeing to reopen the Strait, sparked immediate market recovery.
Despite geopolitical headwinds, underlying economic fundamentals remained constructive. The U.S. ISM Composite Index surged above 50 after three years of contraction, signaling manufacturing expansion. Eurozone business activity accelerated to 51.9 in February, marking 14 consecutive months of growth. Japan’s Tankan survey hit its highest level since Q4 2021, reflecting strong business optimism. Corporate earnings revisions turned positive across most regions, and stock market breadth expanded dramatically—over 50% of S&P 500 stocks outperformed the index by March 31st, reversing three years of narrow market leadership.
Historically, geopolitical selloffs prove short-lived, with average recovery times of 112 trading days and median recovery of just 16 days. Following such events, annualized returns typically range 9.0-10.5% over 1, 3, 5, and 10-year periods. We raised cash during Q1 uncertainty but plan to redeploy into high-quality stocks as clarity emerges. The outlook remains cautiously optimistic if Strait disruption resolves quickly, though extended closure could trigger stagflation and further downside.
Read the full article by clicking below.
First Quarter 2026 Fixed Income Strategy Review
Summary:
Q1 2026 proved a pivotal quarter for fixed income investors, delivering modest but positive returns despite significant market volatility. Government bonds outperformed as yields initially drifted lower through February, before geopolitical tensions surrounding Iran military actions and Middle East energy infrastructure attacks triggered a sharp reversal. Canadian benchmark bond yields surged over 50 basis points, with shorter-duration bonds experiencing steeper increases.
The article highlights critical insights for portfolio positioning. The 2-year bond yield (~2.85%-2.90%) currently exceeds the Bank of Canada’s overnight rate of 2.25%, signaling market expectations for rate hikes within 12 months. However, portfolio managers argue this may be premature given weakening domestic economic growth, subdued job creation, and tightening financial conditions. Governor Macklem’s cautious rhetoric suggests the central bank will remain patient, potentially avoiding rate increases in the near term.
Corporate bonds widened spreads during the quarter due to heightened market uncertainty, yet both investment-grade and high-yield bonds delivered positive returns as coupon payments offset yield increases and spread widening. The strategy emphasizes high-quality corporate bonds to capture attractive yields while maintaining flexibility on duration—avoiding longer-term bond commitments until rates become significantly more attractive.
Looking ahead, the portfolio remains cautiously optimistic. With inflation at the Bank of Canada’s 2% target and no recession anticipated, corporate credit quality remains solid. The approach balances steady income generation with risk management, adapting to emerging opportunities while monitoring geopolitical and trade negotiation uncertainties that could reshape the economic landscape.
Read the full article by clicking below.
First Quarter 2026 North American Equity Strategy
Summary:
In Q1 2026, markets faced headwinds from geopolitical tensions while economic fundamentals remained resilient. The S&P 500 declined 4.33% in dollar terms, though Canadian investors saw improved returns of -2.84% CAD due to currency depreciation. Meanwhile, the S&P/TSX Composite surged 3.94%, driven by energy sector strength.
The Federal Reserve maintained interest rates at 3.50%-3.75%, signaling no rush to cut rates despite persistent inflation concerns. Fed Chair Jerome Powell emphasized uncertainty regarding Middle East developments, with fewer participants now expecting rate cuts in 2026. Economic projections show modest GDP growth of 2.4% for 2026 and elevated PCE inflation at 2.7%.
Historical analysis suggests current conditions differ fundamentally from 1970s stagflation scenarios. Energy intensity has declined two-thirds since the 1970s, and the U.S. is now a net energy exporter, making the economy far less vulnerable to oil shocks. The Misery Index stands at just 6.8%—near “economic nirvana”—compared to 20%+ during previous crises.
Coincident indicators paint an encouraging picture: GDPNow estimates Q1 GDP growth at 2.0%, retail sales rose 6.9% year-over-year, and credit spreads remain below long-term averages. Earnings growth remains robust, with consensus estimates projecting 19.0% growth in 2026 and 16.8% in 2027.
Portfolio adjustments included reducing gold exposure and increasing energy positions, as gold valuations appear near cyclical peaks while energy offers attractive valuations. New positions in Union Pacific and TJX Companies reflect conviction in durable assets and differentiated business models. The outlook remains constructive, with expectations for a relatively swift conflict resolution supporting market recovery over coming months.
Read the full article by clicking below.
The HALO Trade: Why Physical Assets Are Winning Over Software in 2026
Understanding the Shift from Digital to Physical
The investment landscape is undergoing a profound transformation. For the past decade, investors have favored “asset-light” companies—think software platforms and digital services that require minimal physical infrastructure. But in 2026, this preference is reversing dramatically. The market is now rotating toward “asset-heavy” industries: companies that own tangible infrastructure, physical networks, and hard assets that can’t be easily replicated.
This shift is called the HALO trade (Heavy Assets and Low Obsolescence), and it represents one of the most significant portfolio reallocations in recent memory.
Performance of US Asset Heavy (High Capital Expense to Sales ratio) to Asset Light FTW SPX Stock Indices – Past 6 Months, August 2025 to February 2026
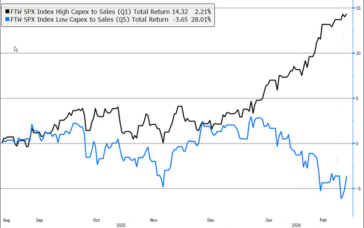
Source: Bloomberg. The above chart shows the outperformance in names that are asset heavy (high capital expense to sales ratio) versus companies that are asset light over the previous 6 months.
Why AI Changed Everything for Software Companies
The catalyst for this change is straightforward: artificial intelligence has fundamentally disrupted the software industry’s competitive advantage.
For decades, software companies enjoyed exceptional profit margins because building quality software required specialized talent, significant time investment, and deep technical expertise. These barriers to entry protected established players like Salesforce, Adobe, and ServiceNow from aggressive competition.
That protection is now gone.
Agentic AI—artificial intelligence systems that can independently write code, manage complex systems, and deploy solutions—has democratized software development. What once took a team of engineers months to build can now be generated by AI in days or weeks. The cost to launch a new software business has plummeted.
This creates a critical problem for established SaaS (Software-as-a-Service) companies: their historically high profit margins are now a target. AI-powered startups can undercut prices, replicate features faster, and compete on terms that were previously impossible. As competition intensifies, those attractive margins will inevitably compress.
The Market’s Response: Repricing SaaS Valuations
Investors are responding rationally to this threat. If software companies face margin compression and increased competition, their long-term profit potential—what analysts call “terminal value”—must be reassessed downward.
This is why we’re seeing valuation multiples compress for software and digital service companies. The market is essentially saying: “We’re less confident in your competitive moat.”
Meanwhile, companies with physical assets—power generation facilities, transportation networks, energy infrastructure, and manufacturing equipment—are gaining favor. Why? Because these assets have inherent protection:
- High replication costs: You can’t easily build a competing power grid or oil refinery
- Long technology cycles: Physical infrastructure remains relevant for decades
- Tangible value: Underground reserves, proprietary equipment, and global networks create genuine scarcity
The Irony: Tech Giants Become Capital-Intensive
Perhaps the most striking development is that the very companies that pioneered the asset-light model—Alphabet, Amazon, and Microsoft—have become the world’s largest capital spenders.
In 2026, these three hyperscalers are expected to invest approximately $500 billion in capital expenditures, representing roughly 32% of their combined sales. They’re building massive data centers, fiber-optic networks, and semiconductor facilities to power AI computing.
The message is clear: Even tech giants recognize that sustainable competitive advantage now requires physical infrastructure.
What This Means for Your Portfolio
The HALO trade reflects a rational reassessment of where value actually resides in the modern economy. Asset-heavy portfolios have significantly outperformed asset-light ones since early 2025, and this trend appears structurally sound.
For investors, this suggests:
- Diversification matters: Overweight positions in pure-play software may face headwinds
- Physical assets offer stability: Infrastructure, energy, and industrials provide tangible value protection
- The digital economy still needs physical foundations: AI and cloud computing require massive physical infrastructure—companies providing that infrastructure benefit from essential, hard-to-replicate assets
The rotation away from SaaS leadership toward physical asset ownership isn’t a temporary market whim. It reflects fundamental economic realities: in an era of abundant digital capacity and AI-driven competition, the assets that matter most are the ones that can’t be easily copied.
